Fixed-Rate vs. Adjustable-Rate Mortgage: How to Choose
A fixed rate never changes. An adjustable rate starts lower and can rise later. Here is how ARMs work, what the caps mean, and when each option makes sense.
Key takeaways
- A fixed-rate mortgage keeps the same interest rate and principal-and-interest payment for the whole loan.
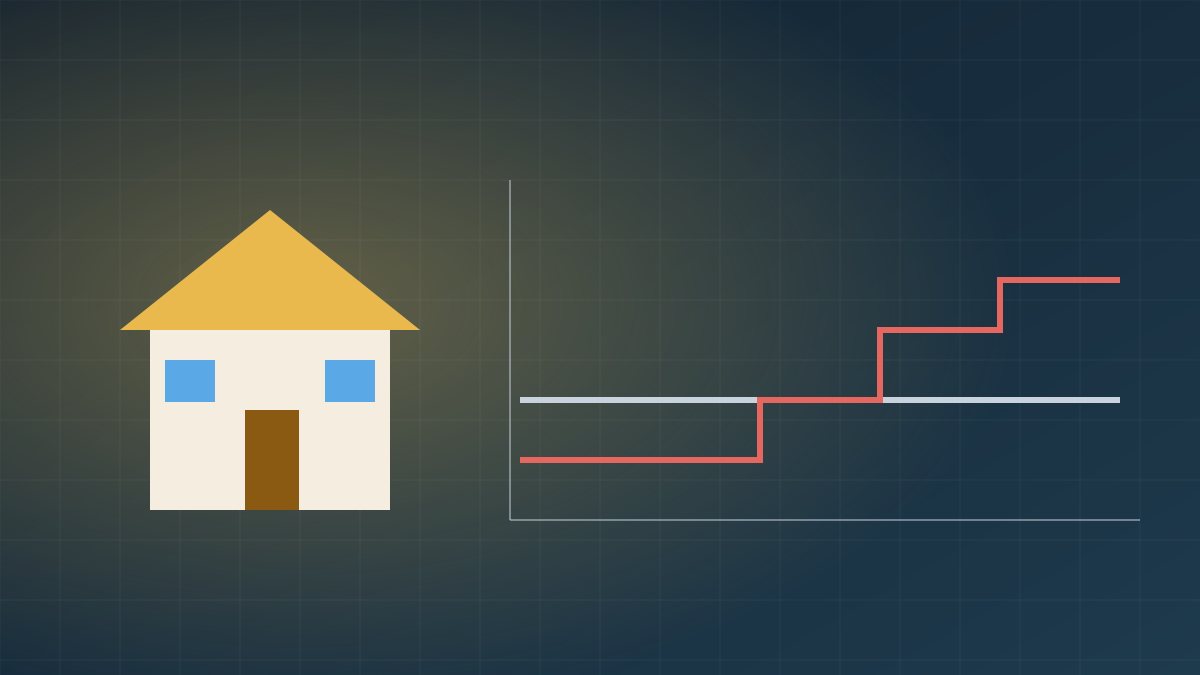
- An ARM has a fixed intro rate for a set period, then adjusts based on an index plus a margin.
- Caps limit how much the rate can rise at each adjustment and over the life of the loan.
- ARMs can make sense if you expect to sell or refinance before the intro period ends.
How a fixed-rate mortgage works
The 30-year fixed is the most common US home loan. Your rate and your principal-and-interest payment stay the same for 30 years, whatever happens to market rates. If rates fall, you can refinance. If they rise, you keep your lower rate. Taxes and insurance can still change your total monthly payment.
How an ARM works
An adjustable-rate mortgage starts with a fixed rate for an introductory period, then adjusts regularly. A 5/6 ARM, for example, is fixed for 5 years and then adjusts every 6 months. A 7/1 ARM is fixed for 7 years, then adjusts once a year.
After the intro period, your rate equals an index plus a margin. Most new ARMs use the Secured Overnight Financing Rate (SOFR) as the index. The margin is set in your loan documents and does not change. If SOFR is 4% and your margin is 2.75%, your rate becomes 6.75%, subject to caps.
Understanding the caps
ARM caps are often written as three numbers, such as 2/1/5:
- Initial cap (2): the most the rate can rise at the first adjustment.
- Periodic cap (1): the most it can rise at each later adjustment.
- Lifetime cap (5): the most it can ever rise above the starting rate.
With a 5.5% start rate and a 5-point lifetime cap, the rate can never exceed 10.5%. Work out what that worst-case payment would be before you sign.
Side by side
| 30-year fixed | ARM (e.g. 7/6) | |
|---|---|---|
| Starting rate | Higher | Usually lower |
| Payment certainty | Full term | Intro period only |
| Risk if rates rise | None | Payment can increase, up to the caps |
| Benefit if rates fall | Must refinance | Rate can fall at adjustment |
| Best for | Long-term owners who value stability | Buyers likely to move or refinance within the intro period |
How to decide
- Estimate how long you will keep the home and the loan.
- Compare the rate gap between the fixed rate and the ARM's intro rate.
- Calculate the ARM payment at its lifetime cap, and make sure you could afford it.
- Ask each lender for a Loan Estimate and the ARM's index, margin and caps in writing.
Run both scenarios in our mortgage calculator: enter the intro rate, then the worst-case rate, to see the payment range. And read How Mortgage Rates Are Set to get the best offer.
This article is general education, not personalized financial advice. Read our editorial policy and disclaimer.